The Core CRA Rule: Use of Borrowed Funds Dictates Deductibility
Under Canada Revenue Agency (CRA) guidelines, the tax deductibility of interest is determined by the purpose and use of the borrowed funds, not by the asset used to secure the loan.
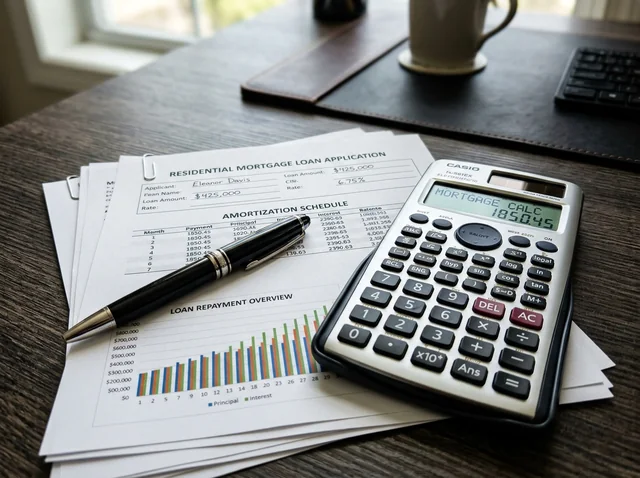
When you borrow money to purchase a home for you and your family to live in, the purpose is personal consumption. Therefore, the interest paid to your lender must be paid using after-tax dollars, with zero offsetting tax deduction available on your annual T1 return.
The Hidden Drag of Non-Deductible Interest
To appreciate why non-deductible debt is an inefficient form of borrowing, consider your marginal tax bracket. If a homeowner is in a 40% combined federal and provincial marginal tax bracket, they must earn significantly more gross income to service every dollar of mortgage interest.
For instance, paying $1,000 in monthly mortgage interest requires earning approximately $1,667 before taxes. This makes non-deductible residential debt one of the most expensive liabilities to carry over prolonged periods.
Contrast with Investment-Purpose Borrowing
When funds are borrowed with a reasonable expectation of producing income—such as purchasing an eligible rental property or income-producing securities—the interest on that specific borrowing may be deductible against the income generated.
Financial educators often discuss the long-term objective of systematically reducing inefficient personal mortgage debt while maintaining disciplined, productive investment habits.
- Personal mortgage: Funded with after-tax earnings; interest provides no tax relief.
- Investment borrowing: Governed by strict CRA tracing rules requiring clear separation of accounts.
- Documentation: Impeccable paper trails are mandatory whenever borrowing across personal and investment accounts.
Strategic Perspectives for Canadian Families
Focusing your prepayment efforts on non-deductible personal debt provides an immediate, risk-free guaranteed return equal to your mortgage interest rate. To discuss how overall financial structuring works, explore our educational services overview.