The True Cost of Debt: Beyond the Headline Interest Rate
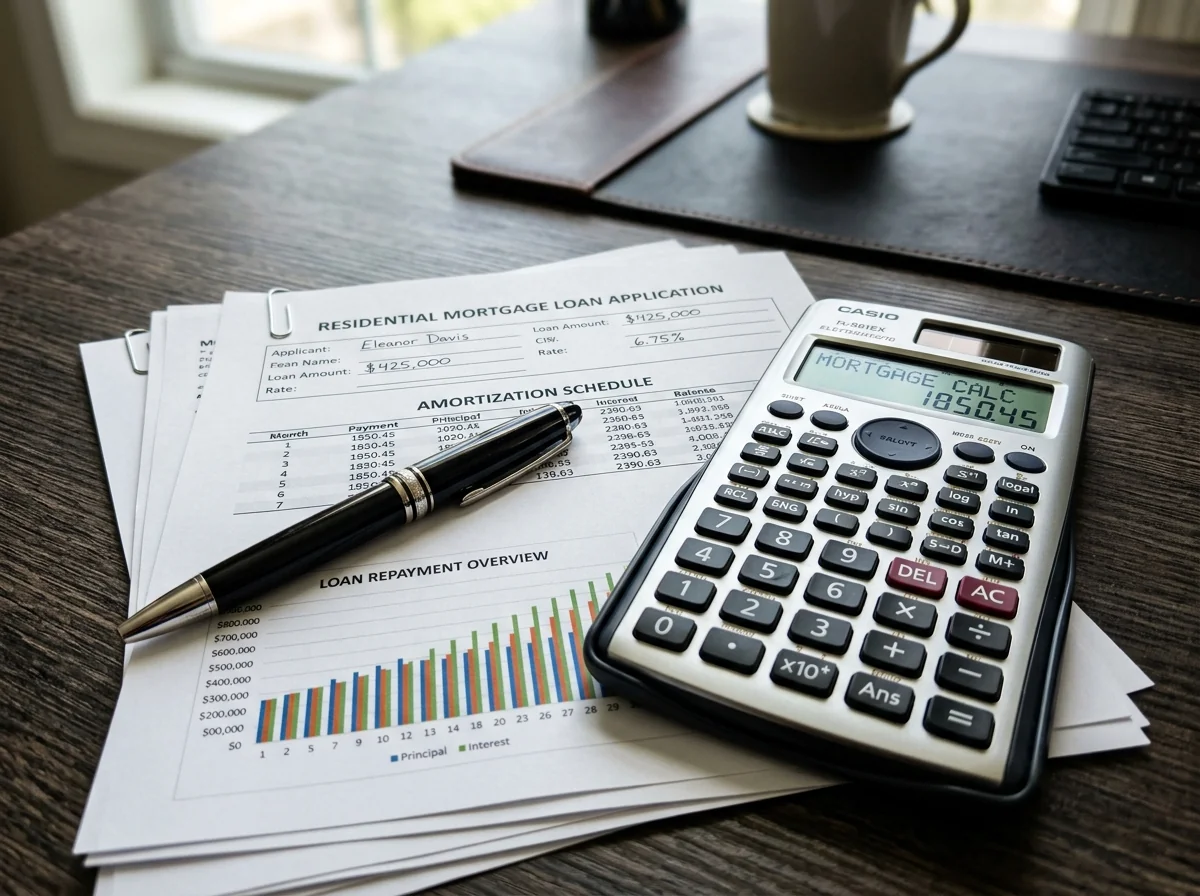
When evaluating a mortgage, homeowners frequently focus exclusively on the posted annual percentage rate. While the rate is undeniably important, contract flexibility, prepayment penalties, portability, and compounding frequency significantly impact the overall lifetime cost.
A mortgage with an aggressive low rate that carries severe restrictive prepayment terms or prohibitive penalties for breaking the contract can cost thousands more than a slightly higher-rate product with robust flexibility.
Understanding Prepayment Privileges
Most Canadian conventional mortgages allow annual prepayment privileges—typically allowing homeowners to pay down between 10% and 20% of the original principal annually without penalty, or increase monthly payments by 10% to 20%.
Applying even modest lump sums directly to principal early in a mortgage term exerts an outsized effect on shortening the total amortization window and saving thousands in cumulative interest.
Evaluating Debt Capacity vs. Household Comfort
Lender qualification formulas measure Gross Debt Service (GDS) and Total Debt Service (TDS) ratios to determine the maximum borrowing limit a bank will approve. However, regulatory approval does not equate to household comfort.
Homeowners should conduct their own budget analysis accounting for property taxes, heating, maintenance reserves, family activities, and retirement contributions to determine their true sustainable carrying limit.
- GDS and TDS limits reflect maximum regulatory capacity, not recommended lifestyle spending.
- Factoring in rising municipal property taxes and insurance premiums avoids budget compression.
- Maintaining separate emergency cash reserves ensures you are not forced into high-interest credit during unexpected repairs.
Integrating Debt Analysis into Family Wealth Planning
Mortgage debt should not be assessed in a silo. How your mortgage interacts with other consumer liabilities and investment assets forms the core of modern financial strategy. To learn more about tax considerations, read our overview of non-deductible mortgage debt.