Amortization vs. Mortgage Term: Clarifying the Difference
Many first-time and seasoned buyers conflate the mortgage term with amortization. In Canada, your term is the duration of your current legal agreement with the lender—usually ranging from 1 to 5 years. When that term concludes, you renew or refinance the remaining balance.
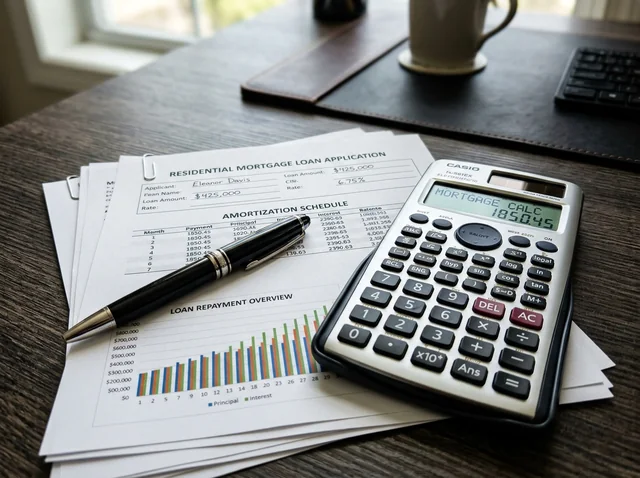
Your amortization schedule, on the other hand, is the full multi-decade roadmap required to reach a zero balance. In Canada, insured mortgages (less than 20% down payment) carry a maximum 25-year amortization, while uninsured mortgages can extend up to 30 years.
The 25-Year vs. 30-Year Trade-Off
Choosing a longer 30-year amortization lowers your mandatory monthly payment, which can provide valuable monthly breathing room or assist with qualification under the stress test.
However, stretching payments across an additional five years means principal is reduced at a noticeably slower pace during the early years, generating substantially higher cumulative interest charges over the life of the loan.
Accelerated Payment Frequencies Explained
Switching from a standard monthly payment to an accelerated bi-weekly or accelerated weekly schedule is one of the most practical, automated ways Canadian homeowners shorten their amortization.
Because an accelerated bi-weekly plan calculates payments by dividing the monthly figure by two and paying 26 times per year, you effectively make one full extra monthly payment directly toward principal each calendar year without feeling a major budget pinch.
- Standard bi-weekly: 26 payments calculated to match the annual monthly total; no amortization reduction.
- Accelerated bi-weekly: Results in the equivalent of 13 monthly payments annually, shaving 3 to 4 years off a 25-year schedule.
- Lump-sum annual prepayments: Applied 100% to principal reduction, compounding future interest savings.
Reviewing Your Amortization Regularly
Whenever you renew or restructure your mortgage, review your remaining amortization to verify you are staying on track with your retirement timeline. For broader strategic planning, see our guide on questions to consider before changing your mortgage strategy.