How Home Equity Actually Accumulates
There are two distinct drivers of home equity growth in Canada: forced savings through contractual principal reduction, and passive appreciation resulting from real estate market value changes.
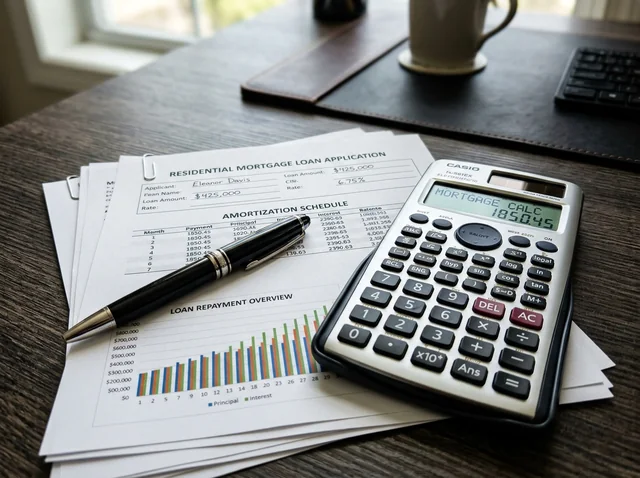
In the early years of a standard 25-year mortgage, the proportion of each payment going toward interest is significantly higher than principal. As the amortization clock progresses, the ratio tilts favorably toward principal repayment, accelerating equity accumulation even without market appreciation.
Appreciation vs. Forced Savings: A Critical Distinction
Market appreciation can create significant equity during favorable cycles, but it can also recede during cooling periods. Relying solely on market price increases to build family wealth introduces volatility into your balance sheet.
Forced savings through disciplined monthly, bi-weekly, or accelerated weekly principal payments represents permanent equity that cannot be erased by local real estate market corrections.
Mortgage Types and Their Impact on Equity
Different mortgage instruments behave differently over time. Fixed-rate mortgages offer total payment and amortization certainty, while variable-rate mortgages with fixed payments may see variable amortization periods during fluctuating interest rate cycles.
Understanding whether your current payments are actively reducing your principal balance or merely servicing accrued interest is a fundamental check every homeowner should perform annually with their lender.
- Fixed-rate mortgages: Predictable principal reduction on an exact, predetermined amortization schedule.
- Variable-rate with adjustable payments: Payments adjust with the prime rate, keeping the amortization timeline steady.
- Readvanceable mortgages: HELOC limits automatically adjust as mortgage principal is retired.
Maintaining Equity Health for the Future
A healthy equity profile gives Canadian families peace of mind, flexibility during unforeseen challenges, and options for long-term retirement planning. For a deeper look at how amortization impacts your total interest burden over time, explore our guide to understanding mortgage amortization.